
INTC stock forecast 2025: intel vs tsmc


Today I will combine the latest trends in TSMC and the chip industry to talk about my views on the trend of TSMC stocks and related semiconductor stocks. The biggest news in the past few days is that Intel has invested 20 billion US dollars to build factories and enter chip foundry.

Intel (INTC) stock forecast 2025

Intel (INTC) stock forecast 2025

Intel’s new CEO Pat Kissinger released the ambitious "IDM 2.0" strategic plan on March 24

In summary, on the one hand, Intel will separate the chip manufacturing part and open up production capacity to provide foundry services. On the other hand, its own chips will expand the scope of finding other foundry companies.

For example, looking for foundries such as TSMC and Samsung, we can interpret that Intel’s future business will have two parts: one is the foundry part and the other is the chip design part. If you look at Samsung Electronics, it originally has these two parts. Samsung’s chips are produced entirely by its own foundry company

This is because Samsung’s foundry capability is second only to TSMC. Samsung will not find other companies to do foundry. Intel’s approach is very common in this industry. GlobalFoundries was actually independent of AMD in 2009.

The separation of chip design and foundry is the general trend of this industry. Intel's move to this general direction under the new CEO's leadership is also in line with the trend of the times.

In line with market expectations, let’s analyze the impact on TSMC. Intel’s entry into the foundry industry’s competition has made companies on the foundry track even more crowded. Intel announced that it has broken through the EUV-based 7-nanometer process. I think we Think of it as TSMC, the third-largest in the industry, and Samsung, the second largest in the industry, has mass-produced EUV-based 5-nanometer processes.

What are the advantages of Intel foundry?


First, it can be expected that Intel’s chip design company should try to find its foundry company to do foundry. This is the same as Samsung’s strategy. Only those that cannot be done by themselves will be handed over to TSMC and Samsung. Therefore, Intel wafer generation The company’s biggest customer will actually be itself

Since Intel is the industry leader in chip design, the starting point of Intel foundry company is very high.

Second, most of Intel’s factories are located in the United States and Europe, and most of its foundry customers are also customers in the United States and Europe, such as Microsoft, IBM, Cisco, etc.

Compared with TSMC and Samsung, Intel is closer to its customers and easier to communicate with.

Third, needless to say, the United States will provide Intel’s foundry with financial, material, and human resources at the government level. Intel is the pride of the US IT industry. It is a truly American company and possesses American core technology. The establishment of factories and foundry in the United States is in the national interest of the United States

Based on the above three points, we can see that Intel’s foundry will have a certain impact on TSMC and Samsung.

Let's analyze the disadvantages of Intel's foundry


 First, it is a huge change from serving internal customers to serving external customers. This transformation is not easy to succeed.

Second, the cost in the United States is higher than that in Asia. Therefore, whether Intel can maintain its competitiveness in terms of price is still a problem. This was the reason. The foundry industry gradually shifted to low-cost Asia. GlobalFoundries with similar origins could not compete with TSMC and Samsung. Intel is hard to say there is a big opportunity

Third, many potential customers will be competitors of Intel, such as AMD, Nvidia, Qualcomm, etc. These companies will be more inclined to choose TSMC

Fourth, Intel has just broken through 7 nanometers and TSMC and Samsung have already mass-produced 5 nanometers a year ago. This determines that Intel, TSMC, and Samsung are not completely on the same subdivision track. Apple and Qualcomm’s latest mobile phone chips must It’s impossible to grab such customers with 5nm Intel

So, based on the above, my views on Intel's reform are as follows:


First, Intel’s reform is more focused on maintaining the leading position of Intel’s chip design, using the latest third-party manufacturing process to make its products maintain an advantage in the competition with AMD and Nvidia.

After all, Intel’s chip design is its core competitiveness. Intel’s chip design is the main body of Intel in the future. This is exactly the same as AMD’s original intention to spin-off GlobalFoundries.

Second, Intel’s current reform is more about stripping off the chip manufacturing part and allowing it to find work in the market, which may lead to fate. Intel’s new boss will of course not say so, but is more optimistic and emphasizes letting Intel work in foundry Look for opportunities

Third, this reorganization is good news for Intel. Intel is looking for a foundry, which can reduce costs, provide product competitiveness and breakthrough 7-nanometer technology, open up manufacturing capacity, and look for more business opportunities. Therefore, at this stage, the market recognizes Intel. Restructuring

However, in the long run, it depends on Intel’s performance. Intel has been severely suppressed by AMD in the past few years. Once found TSMC’s foundry, Intel uses the 5-nanometer process, Intel’s competitiveness will be greatly enhanced.

For AMD, Intel’s rebirth is definitely bad news. AMD’s short-term stock trend will definitely be under pressure.

Fourth, for TSMC, I think there is mixed good and bad news. 

tsm eps

The good news is that with Intel’s manufacturing outsourcing, TSMC as the industry leader, Intel as such a large quality customer, it is certain that TSMC’s short-term revenue will increase.

The worry is that TSMC has a strong potential competitor for foundry

I personally think that in the short term, there are more joys than worries. In the long term, it is difficult to tell. It really depends on the progress of Intel’s process technology and the evolution of the industry.

I’m not very optimistic about the foundry part of Intel. I think it might end up as a second-tier competitor like GlobalFoundries. Intel has not done well in the manufacturing process in the past few years, and it will not be suddenly reborn as a result of this reform.

TSMC’s leadership is based on many advantages that cannot be replicated, such as cost, competitiveness in Asia, high R&D investment in the past, and close relationships with customers, etc.

Fifth, who is the biggest beneficiary of this Intel reform? Of course, it is ASML
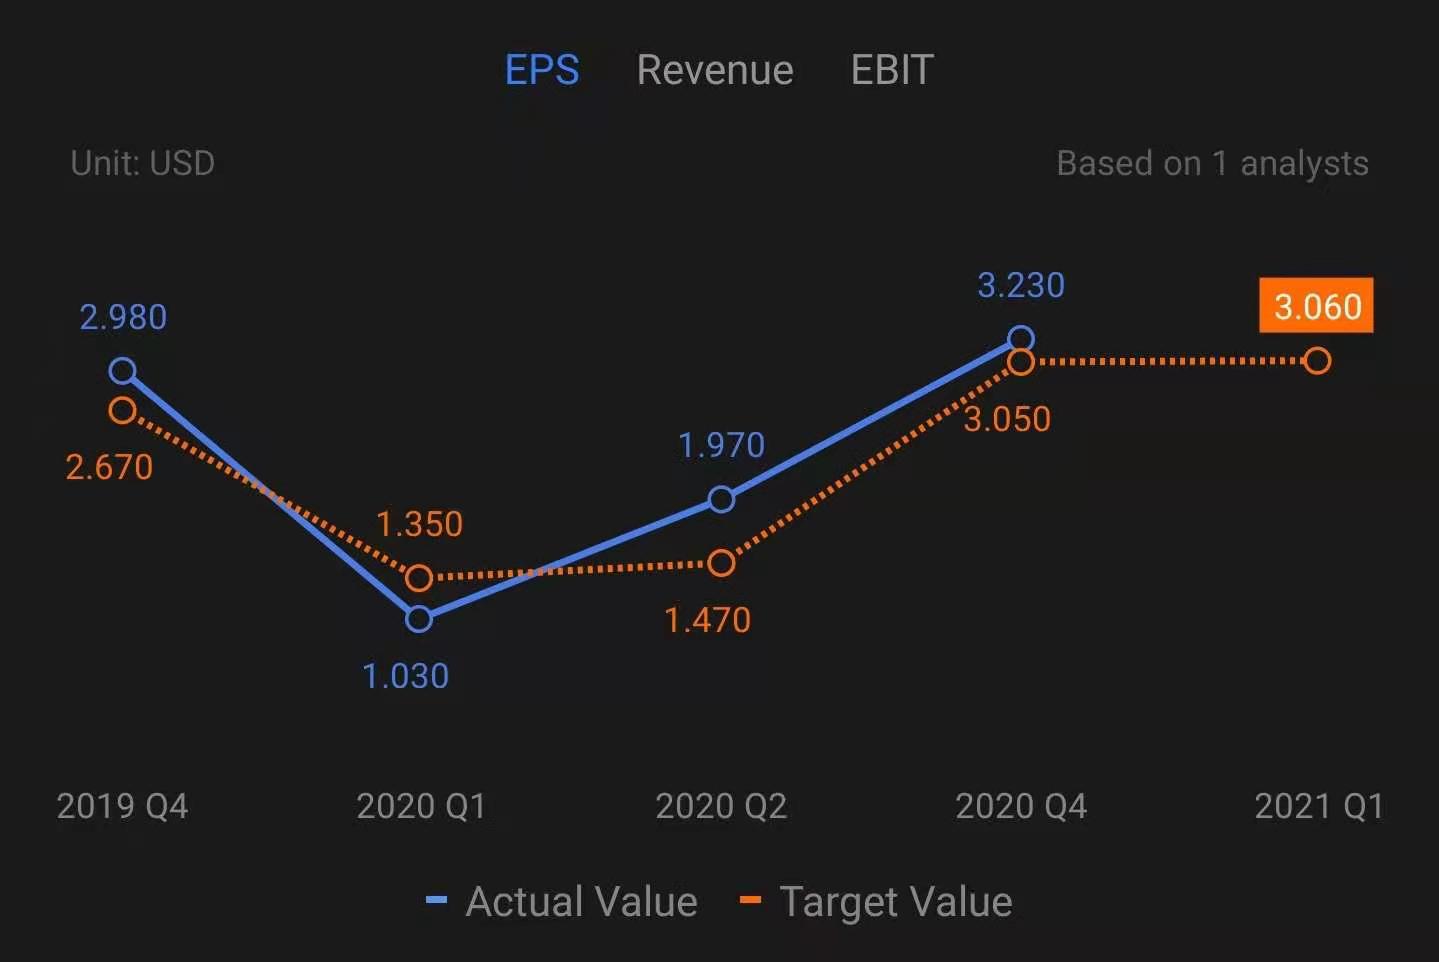
asml eps

 Intel increases its investment and will purchase a large number of EUV lithography machines. At the same time, competition intensifies, TSMC and Samsung will spend more money on research and development of high-end processes. Therefore, ASML, which monopolizes EUV lithography machines, will have good growth in the future.

Finally, talk about my views on TSMC stocks and related semiconductor stocks. With this round of adjustments to technology stocks, the price of TSMC in the U.S. stock market has been adjusted from the highest of US$142 to about US$110.

Intel’s entry into the foundry market will make investors more worried that competition will bring short-term pressure on TSMC’s stock price. However, I think TSMC’s adjustments will also give investors who have not entered the market a golden opportunity to buy. Because TSMC can adjust to below $100 because of this negative news, it should buy without hesitation.

I have analyzed that Intel is looking for TSMC's foundry. The recent shortage of chips determines that TSMC's performance in 2021 will be very good in the long-term. The entire chip industry is thriving and the demand for foundry is strong, and there is no major problem in the entire industry. Intel's entry into the foundry industry currently sees little impact on the far-leading TSMC

And we just analyzed that Intel’s foundry may always be a second-tier competitor.


Just like there is another GlobalFoundries and SMIC. TSMC’s true competitor is still Samsung. Facing the competition,

I believe that TSMC, which has the right time, location, people, and advantages, will continue to stay ahead. Therefore, if you, unfortunately, buy TSMC during this adjustment of technology stocks and get trapped, I think you should hold Intel. The short-term negative news will pass sooner or later, and in the end, the performance will have the final say.

If you want to invest in TSMC for a long time, the recent adjustment is a once-in-a-lifetime opportunity to enter the market. Also, if you want to hedge risks, the intensified competition in foundry has made ASML sit back and reap the benefits, and it is also a good long-term investment choice.

In the chip design industry, it’s not easy to analyze thoroughly. It’s hard to say that Intel will change its structure and become the ultimate winner in the long-term.

At the same time, AMD will not wait to die. It is even more difficult to judge the future of Intel’s foundry part. At this stage, it is not possible to judge clearly by Intel CEO's ppt alone.

In any case, after all, the entire chip design industry is still very promising. The ups and downs of individual companies are sometimes not easy to see really. If you are like this, I think you can hold the chip design industry through ETFs such as tracking the Philadelphia Semiconductor Index. ETF SOXX


Related articles

Comments

Popular posts from this blog

The five stages of company growth!

company Many people who study stocks will analyze the fundamentals of the stock, such as viewing its performance report, PE, PB, PEG, debt ratio, dividend ratio, cash flow, ROE, EPS growth, etc. I don't know if you tried it. After performing many basic analyses, you will feel that the prospects for a particular stock are very good.  You have even read the analysis reports of many large banks, or listened to the analysis of many market participants and obtained a consistent high evaluation.  Then, you will think that this stock will grow in the future, so you buy it and think that you can use this stock to create a better future from now on, and the final development of the story is the opposite of the fact that the development direction will eventually Put you in trouble or lose money. I will not deny the importance of basic analysis, because, in addition to focusing on technical analysis, I am also very concerned about the company's basic factors. I am an investor fo...

4 George Soros advice to investors!

Who is George Soros? George Soros is a Hungarian-born Jewish businessman. It is one of the most influential investors in the world. In 1969, the Double Eagle Fund was established for Arnhold & S. Bleichroeder, an investment management company. In 1973, Soros and his assistant Rogers left Bleichroeder to co-found Soros Fund Management. In 1979, the well-known Quantum Fund was established and continued to make profits. In the Asian financial turmoil in 1997, George Soros sniped the Thai baht and the Hong Kong dollar, which was frightening. Learning from the experiences of successful people can benefit a lot. Here are 4 tips George Soros gave investors. First, to be successful, you must have ample free time. Most people want to be rich, but not everyone realizes the importance of free time. Many people spend a lot of time working to accumulate wealth, sleep, and forget. Set the goal to complete the work indicated by the superior, or the needs of business partners. But they hav...

INTC stock forecast 2025: Intel's acquisition of SiFive

SiFive, a chip design start-up company based on the RISC-V instruction set architecture, has received an acquisition intention from investor Intel.  A person familiar with the matter, who asked not to be named, said that Intel has offered to buy SiFive for more than $2 billion.  RISC-V with x86 and Arm  As we all know, Intel dominates the industry leader in x86 architecture chip technology, while SiFive focuses on open-source RISC-V technology and employs several founding members of the RISC-V architecture.  For a long time, the field of CPU instruction set architecture has been dominated by x86 and Arm. Since RISC-V was born at the University of California, Berkeley in 2010, it has gradually formed a certain competitive landscape with Arm after more than ten years of development.  With the gradual refinement of the application field, the model of one chip making the world has become a thing of the past. Facing the hot AI and Internet of Things market, RISC-V i...

Catherine Wood's Disruptive Innovation ETF: Is ARKK worth buying?

  ARKK ETF by Catherine Wood  Catherine Wood's Disruptive Innovation ETF  Warren Buffett is a stock god that everyone respected in the past, but in the past year, the female stock god Catherine Wood has become famous for the rising trend of technology stocks, and his head completely overshadows Buffett.   Therefore, this time I want to talk to you in detail about the prestigious history of this female stock god.  Catherine Wood founded ARK Investment in 2014 and listed the funds under her management under Exchange Traded Funds to facilitate investors to buy and sell, but the management fee is as low as some passive funds that track an index, about 0.75% per year.  Ark Investment launched 4 ETFs in September and October 2014. The themes are Next Generation Internet, Automation Technology and Robots, Innovative Technology, and Genetics.  Among them, Innovative Technology is currently the flagship ETF of Ark Investment and the most most popular ETF w...

The signal that the stock market has peaked?

the stock market Although I know how to judge when the bear market is over and when I should buy at the bottom, I still don't know how to judge the selling at the top. I'm afraid I don't know when to leave the market after buying stocks in the future. If you have also tried to avoid the crash, stock market crash, and even bear market, or always hold stocks at these times. These four tricks are based on my experience in the stock market for more than 10 years. They help me hold cash early before many market declines, so I suggest that you must see the end. It is likely to help you invest in stocks.  Raise to another level. Because knowing how to go is more important than knowing how to buy, and knowing how to go is an important factor in determining how much you can earn or lose. The first trick, everyone needs to learn to identify the Distribution Day. As the name implies, the shipping day is a day of huge selling pressure. On that day, it may be that large account...

Disney stock forecast 2025: Is it time to buy now?

  The much-watched Disney released its second quarter financial report this year.  Benefiting from the strong recovery of theme parks and the rapid growth of streaming media business, its net profit and revenue both beat expectations.  Disney's stock price rose 5% after the market.  Let's take a look at the highlights of Disney's earnings this quarter.  In the second quarter, Disney’s total revenue reached 17.02 billion US dollars, exceeding analysts’ expectations of 16.76 billion US dollars, a year-on-year increase of 45.5%.  Net profit turned from loss to profit, from a loss of US$4.721 billion last year to a profit of US$918 million.  From the perspective of departmental business, Disney Parks, Experience and Products departments have brought a boost to the company's revenue.  Since the economic restart, Disney's theme parks, cruise ships and offline merchandise retail businesses have all been greatly improved. The quarterly revenue of these bu...

Will the Great Depression make a comeback?

the Great Depression On March 21, 2020, the United States already had initial unemployment data. Exceeding market expectations, the number of applicants reached 3.28 million, a record high. The current unemployment situation in the United States. Before March 7, employment in the United States was not affected by the epidemic. In the week of March 7, the number of people applying for unemployment benefits for the first time in the United States was 211,000, a decrease of 4,000 compared to the previous week. It is still healthy. This shows that the United States is in a good employment track range. The actual data began to fluctuate, that is, the data for the week of March 14, the number of people applying for relief reached 282,000, a slight increase. On March 21, the number of people applying for unemployment benefits soared to a record high this week. 1.7 million people have far exceeded expectations, and market expectations are about 1.5 to 1.7 million people. It can be said...

Why has international oil(USO) prices plummeted?

As OPEC and Russia failed in negotiations and could not reach an agreement to reduce production, Saudi Arabia issued a comprehensive production increase announcement. Russia followed Saudi Arabia to increase production.  Due to the sharp increase in oil supply, international oil prices plummeted, and US stocks were affected by the spread of the epidemic, and international oil prices The plunge, the U.S. stock market plummeted, triggering multiple fuses. S&P500 Index Oil is a commodity whose price is affected by supply and demand. When oil production increases, supply increases, prices fall, and at the same time affected by the epidemic, demand decreases, and prices also fall. Oil supply increases and demand decreases, which is the main cause of the plunge in international oil prices. In terms of oil supply, since the United States developed shale oil, US oil production has become the world's largest. The production cost of shale oil is more than US $ 40, which is the ...

Cloudflare's 4Q 2021 earnings report

 Just took a look at Cloudflare's (NET) 4Q 2021 earnings report. Cloudflare is in an area that covers several hot spots, including content delivery networks, i.e. CDNs, cloud computing, and cybersecurity. For the Cloudflare quarterly report, here is a summary: 1) Revenue of $194 million (then expected 4Q revenue in the range of $184 to $185 million), up 52% year-over-year ($172 million in 2021, up 51% year-over-year). 2) The number of customers continues to grow rapidly, with the total number of customers has reached 1416 (1260 in the previous quarter). 3) Non-GAAP gross margin was 79.2% vs. 78.1% in the same quarter last year (vs. 79.2% in 3Q vs. 77.3% in the same quarter last year.) Non-GAAP net income has started to turn around, meaning it has started to be profitable. 4) Revenue is expected to be in the range of $205 to $206 million in 4Q. That works out to about 6% YoY growth. Cloudflare had good results this time, beating its previous guidance. Revenues are still growing at a...

PLTR stock forecast 2025: Cathie Woods increased Palantir stock position

Software company Palantir (PLTR) released the latest quarterly earnings report, which performed very well.  After the financial report, Palantir's stock price soared to 14.64% at the highest point. At the same time, the keen Cathie Woods also bought $140 million in Palantir stock.  I won't talk about Palantir's specific business. If you don't know much about it, you can go back to my previous article.  Let's talk back to the financial report.  Benefiting from the benefits of the US government’s contract renewal, Palantir’s earnings per share and total revenue both beat expectations for this quarter’s earnings report.  Among them, earnings per share were $0.04, beating the expected $0.01; total revenue was 376 million, an increase of 49% from the same period last year, slightly higher than the expected $361 million.  Although the extent of beating expectations is not very large, the biggest highlight of the financial report is to broaden the business.  ...